
Table of Contents
- Why Insurance Companies Make Low Settlement Offers
- Step 1: Review Your Policy and the Settlement Offer Carefully
- Step 2: Documenting Property Damage for Insurance Claims
- Step 3: Writing an Insurance Claim Demand Letter Template
- Step 4: How to Write a Counteroffer and Negotiate with Adjusters
- What Is a Public Adjuster and When Should You Hire One?
- How Long Does an Insurance Claim Dispute Take?
- Frequently Asked Questions
Last Updated: September 16, 2026
Why Insurance Companies Make Low Settlement Offers
A low settlement offer is rarely a mistake, it is a calculated opening bid, and the first number an adjuster names is almost never what they expect to pay.
Three forces drive the initial offer down:
- Reserve targets. Adjusters work against internal payout goals, so the first offer protects the carrier’s loss ratio.
- Incomplete documentation. If your file lacks contractor estimates or photos of hidden damage, the adjuster prices what they can see, not what you actually lost.
- Speed pressure. Carriers know most policyholders are stressed and want the claim over with.
Step 1: Review Your Policy and the Settlement Offer Carefully
Before responding, read your policy and the settlement breakdown side by side.
Look for these specific items in the settlement letter:
- The line-item repair estimate and whether it matches your contractor’s scope
- Any depreciation withheld and whether it is recoverable
- Deductible application and coverage limits
- Exclusions the adjuster cited
Step 2: Documenting Property Damage for Insurance Claims
Documenting property damage for insurance claims means building a file so complete the adjuster has no reasonable basis to dispute it. Photos, video, receipts, and independent estimates do that work for you.
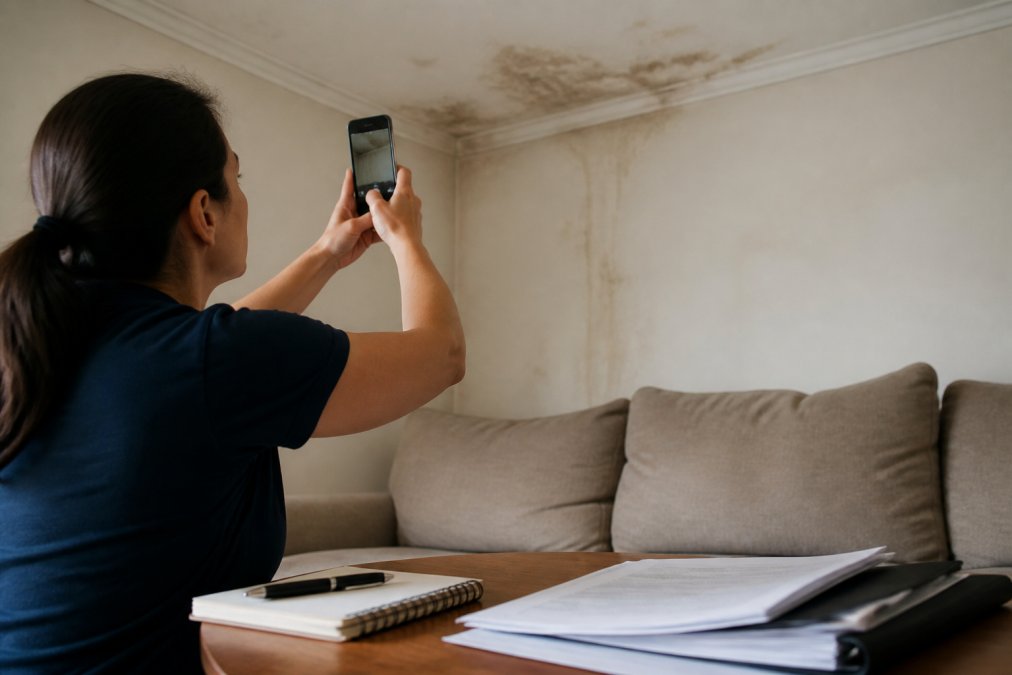
- Photograph every affected area from multiple angles, with a wide shot and a close-up
- Film a slow walkthrough video narrating what you see
- Keep every receipt: hotel stays, meals, equipment rentals, temporary repairs
- Get written estimates from at least two licensed contractors
- Save all correspondence with the carrier, including emails and call logs
What Evidence Is Needed to Dispute a Low Settlement Offer
The strongest dispute file has four categories: proof of damage (photos and video), proof of cause (a plumber’s report or roofing inspection), proof of cost (contractor estimates), and proof of loss (out-of-pocket expenses and lost wages if the property was uninhabitable).
Step 3: Writing an Insurance Claim Demand Letter Template
Here is a working template you can adapt:
[Your Name]
[Property Address]
[Date][Adjuster Name], Claims Department
[Insurance Company]
[Claim Number: XXXXXXXX]Dear [Adjuster Name],
I am writing to formally dispute the settlement offer of [amount] dated [date] for claim [number]. Based on the enclosed documentation, the actual covered loss is [amount].
The offer undervalues the claim for the following reasons:
- [Reason, with reference to enclosed evidence]
- [Reason, with reference to enclosed evidence]
Enclosed please find: contractor estimates, photographs, receipts, and a line-item comparison of your estimate against the actual repair scope.
I am requesting a revised settlement of [amount] within 15 business days. If we cannot reach agreement, I am prepared to pursue appraisal, mediation, or other remedies available under my policy and state law.
Sincerely,
[Your Name]
[Phone] | [Email]
Key Components of a Formal Demand Letter
Every effective demand letter includes five elements: the claim number and policy reference, a clear statement of the disputed amount, the specific reasons the offer is inadequate, the supporting evidence attached, and a deadline with a stated consequence. Skip one and it reads as a complaint, not a demand.
Keep it factual. Adjusters respond to documentation, not frustration.
Schedule your FREE Claim Consultation today →
Send the demand letter with a return receipt requested, and reference the certified mail number in every follow-up. It creates a paper trail that makes delay tactics visible if the dispute escalates.
Step 4: How to Write a Counteroffer and Negotiate with Adjusters
A counteroffer is your written response proposing a specific higher figure backed by evidence, not a request, but a number with a rationale. Base it on contractor estimates and documented expenses, not what you feel you deserve, adjusters dismiss emotion and engage with line items. The first counteroffer typically lands between the initial low offer and your documented number, and each exchange narrows the gap until the adjuster’s authority limit is reached.
Common Insurance Adjuster Tactics to Watch For
Adjusters use predictable pressure tactics, and recognizing them in the moment is half the defense:
- The “final offer” claim. Often it is not final. Ask for the denial in writing.
- Delays. Silence is a tactic. Follow up in writing every two weeks.
- Depreciation disputes. Ask whether withheld depreciation is recoverable once repairs are complete.
- Causation shifts. An adjuster may attribute damage to wear and tear rather than a covered event. Your documentation should address this directly.
- Quick-settlement pressure. Urgency benefits the carrier, not you.
The Psychology Behind the Lowball: Anchoring and Time Pressure
Most guides stop at listing tactics. The mechanism matters more, because once you see it you can neutralize it.
Before any phone call with an adjuster, write down your three non-negotiable line items and your walk-away number. Adjusters are trained to read hesitation; a written script removes the improvisation they exploit.
Sample Counteroffer Language
“Thank you for the revised offer of [amount] dated [date]. Based on the enclosed contractor estimate of [amount] and documented out-of-pocket expenses of [amount], the covered loss remains [amount]. The current offer is [amount] below the documented scope. I am requesting a revised settlement of [amount] within 15 business days. If we cannot reach agreement, I am prepared to invoke the appraisal provision of my policy.”
Never sign a release of liability or settlement agreement until you are certain the figure covers the full repair scope. Once signed, the claim is closed and reopening it is extremely difficult.
What Is a Public Adjuster and When Should You Hire One?
A public adjuster is a licensed professional who represents the policyholder, not the insurance company, during a property claim, evaluating your policy, documenting damage, preparing the claim, and negotiating directly with the carrier.
- The claim is complex, large, or involves disputed causation
- Your claim was denied or significantly underpaid
- You lack the time or documentation to build a full dispute file
- The carrier’s appraiser disputes your contractor’s scope
How Long Does an Insurance Claim Dispute Take?
An insurance claim dispute typically takes a few weeks to several months, depending on complexity, the carrier’s responsiveness, and whether it escalates to appraisal or litigation.
| Dispute Path | Typical Timeline | Best For |
|---|---|---|
| Written counteroffer | 2-6 weeks | Clear scope disputes |
| Formal appraisal | 1-4 months | Valuation disagreements |
| Mediation | 2-5 months | Stalled negotiations |
| Litigation | 6+ months | Denials and bad faith |
What Actually Drives the Timeline
Three variables move the clock most:
- Documentation completeness. A file with contractor estimates, photos, and receipts moves; a thin file stalls while the adjuster requests more.
- The dispute path. A counteroffer is fast because it stays inside the claims department; appraisal and mediation pull in third parties, adding scheduling time on both sides.
- Carrier responsiveness. Most states have prompt-payment and claim-acknowledgment rules requiring the carrier to respond within set windows. When those windows pass without a response, that silence is itself evidence you can document.
When a Low Offer Crosses Into Bad Faith
A low offer is not automatically bad faith. Adjusters have authority limits, and opening low is standard practice. The line is crossed when the carrier’s conduct departs from its duty to handle your claim fairly and in good faith.
- No reasonable basis for the denial or valuation. The carrier’s stated reason contradicts the evidence in your file, for example, attributing storm damage to wear and tear despite an inspection report saying otherwise.
- Failure to investigate. The adjuster never inspected, never requested your documentation, or ignored your contractor’s estimate entirely.
- Unreasonable delay. The carrier misses statutory claim-handling deadlines without explanation, or repeatedly requests the same documents.
- Misrepresenting policy language. The carrier cites an exclusion that does not appear in your policy, or misstates your coverage limits.
- Lowballing with no explanation. An offer far below the documented scope with no line-item justification.
Deadlines You Cannot Miss
Two clocks run in parallel during any dispute:
- The statute of limitations. Every state sets a deadline for filing suit, varying by claim type and state. Once it passes, you lose the right to sue regardless of how strong your evidence is. Confirm the deadline for your claim type early, in writing, and calendar it.
- Policy-imposed deadlines. Many policies require you to submit proof of loss, demand appraisal, or file suit within a set period after the loss. These are contractual and can be shorter than the statute of limitations.
Your roof is leaking now, and that urgency is real. But accepting a low settlement offer to end the process faster usually costs more than the delay. The Florida Department of Financial Services consumer claim resources explains the timelines and remedies available to policyholders, and the USA.gov guide to filing an insurance complaint covers what to do if a carrier acts in bad faith.
Timelines vary, but the quality of your documentation is the single biggest factor in how fast a dispute resolves. A complete file moves; a thin one stalls. And if the carrier’s conduct, not just its number, is the problem, document the pattern early; bad-faith claims are built on a paper trail, not a single low offer.
Frequently Asked Questions
What should I do if my insurance settlement offer is too low?
Do not accept it immediately. Request a written explanation of how they calculated the offer, then gather your own evidence like contractor estimates, photos, and receipts. Write a formal demand letter with your documented claim value and a counteroffer. If the adjuster won’t budge, consider hiring a public adjuster or attorney. Many initial offers are intentionally low, so pushing back often results in a higher payout.
How do I write a counteroffer letter for an insurance claim?
Start with your policy number and claim details. State the settlement amount you received and why it’s insufficient, citing specific evidence like medical bills, lost wages, or repair estimates. Include a demand letter template with your calculated fair market value. Reference policy limits and any bad faith concerns. End with a deadline for their response. Keep it professional and factual, not emotional.
How long does an insurance claim dispute take?
Timelines vary by complexity. A simple counteroffer might resolve in a few weeks. If you hire a public adjuster or attorney, the process can take several months. Litigation may extend it to a year or more. Factors include the insurance company’s responsiveness, the evidence you provide, and whether the dispute goes to appraisal or court. Patience and thorough documentation speed things up.
Should I hire a public adjuster to help with a low settlement offer?
If your claim is complex or the offer is far below your documented damages, a public adjuster can help. They review your policy, document damage, and negotiate directly with the insurer. They work on a contingency fee, so you pay nothing unless they recover more for you. For straightforward claims, you may handle it yourself, but for large losses, their expertise often pays off.